Search this site
196 results found with an empty search
- What Buyers Want to See in Behavioral Health Leadership Teams
By Kevin Taggart, CM&AP, Managing Partner, Mertz Taggart At a Glance Buyers evaluating a behavioral health leadership team want evidence that the business can operate through an ownership transition. They examine who makes decisions, who is accountable for finance and compliance, and whether key people intend to remain. The structure should fit the business’s size and care model, with responsibilities demonstrated in day-to-day work. A buyer evaluating your behavioral health business will want to understand how much of the operation depends on you, and the answer shapes how they assess the transition they are taking on. That question is worth working through before a sale process starts, particularly if you plan to step back afterward. There is no single organizational chart that solves this for every practice. The useful starting point is the work itself: who is doing it, who has authority to make decisions, and where the operation still needs more support. Look at the decisions that reach your desk One way to assess founder dependence is to look at your own day. Which decisions genuinely need your involvement? Which ones come to you because responsibility has never been assigned elsewhere, or because the team is used to checking with you first? That review can reveal where management capacity needs to develop. Buyers will ask about those same responsibilities. They want to understand how the business handles operating questions, how performance is reviewed, and who follows through when something needs attention. A capable second-in-command can make a meaningful difference, especially when that person already leads substantial parts of the operation. Give people the authority and support to carry their responsibilities, then allow time to see how the arrangement works. If you plan to reduce your involvement, the business benefits from making that change deliberately. You also gain experience you can draw on when a buyer asks how the company would operate after you step back. Use the organizational chart to explain those working relationships, including where responsibilities overlap or still depend on you. → Related: How to Prepare Your Behavioral Health Business for Sale in 2026 Match leadership investment to the business It can be difficult for a smaller behavioral health business to support a full executive team. Buyers understand that. Before adding a senior role, look at the responsibility that needs to be covered and whether the business can sustain the cost. Financial management is a good example. You need reliable reporting and someone who can explain the numbers. A controller may provide that capability at the company's current size. As the business becomes larger or more complex, its needs may justify a CFO. That decision should reflect the complexity of the work and what the business can afford. As the organization grows, business development or corporate development roles may help it expand into new locations or pursue acquisitions. Consider whether someone needs to take responsibility for that work, how the role would change your own involvement, and whether the business can support the investment. Clinical and operating leadership need to fit the care model as well. A structure that works for one behavioral health provider may leave gaps in another. Work through the functions your business depends on, identify who is accountable, and assess where that person needs help. This produces a more useful plan than trying to copy the management team of a much larger company. Give compliance the attention it requires Compliance needs a clear place in the management structure. Before adding another executive title, establish who oversees clinical documentation and billing, who receives concerns, and who has authority to act. That person also needs access to the appropriate expertise, and you should be prepared to explain how management follows through when an issue is identified, with records that support the account. Address retention and the owner's future role A leadership team is most valuable to a buyer when the people the business relies on are available to continue doing the work, and turnover gets attention accordingly. If retention has been difficult, understand the reasons and be prepared to explain how management has responded. Compensation, workload, and employee satisfaction may all be relevant. So are the effects on hiring costs and the practice's ability to maintain its operation. A buyer will learn more from an accurate account of those issues than from a general statement that the company has a strong culture. The intentions of key leaders also matter, but discussing a potential sale with employees requires care. Work with your advisor on whom to involve and when. Confidentiality and the buyer's need to understand leadership continuity have to be managed together throughout the process. Be equally clear about your own plans. If you want to leave after a transition period and a buyer expects you to lead the business for several years, that needs to come out before you select its offer. Your future role is part of the transaction you are negotiating. Key Takeaways Know which decisions already reach the team without you, and be prepared to demonstrate that. Match leadership investment to the complexity and scale of the business, not to what a larger organization would carry. Give financial reporting and compliance a named owner with a documented track record. Resolve your own post-sale role before you select an offer, not after. Building management depth takes time because people need the chance to lead before anyone can evaluate the result. If a sale is on your horizon, look at the responsibilities you would want the team to carry without you and begin there. I’d be glad to talk through it, confidentially. → Related: Selling the Practice You Built
- What Makes a Mental Health Practice Scalable
By Kevin Taggart, CM&AP, Managing Partner, Mertz Taggart At a Glance Buyers assess a mental health practice’s scalability through demonstrated revenue and earnings growth, the team’s capacity, and the systems behind the operation. They want to understand whether expansion can remain profitable and whether the business can keep performing beyond the founder. A forecast carries more weight when it builds on results the practice can support. Opening another location can be a big step for a mental health practice. You have to find the rig ht clinicians, put support in place, and decide whether the business can carry the additional cost. If you are also thinking about an eventual sale, you may wonder how much of that work will show up in the value of the company. The first place we look is the performance you can demonstrate. Has growth produced additional earnings? Can the team manage the larger operation? If you have expanded successfully, what would it take to do it again? Those questions help a buyer understand whether the next stage of growth is a reasonable extension of the business you have built. A forecast has a place in that discussion, especially when an expansion is still getting established. Its credibility comes from the results and operating decisions behind it. That is where an owner can do useful work well before going to market. Start with what the practice has already achieved If you have opened another location, be ready to walk through how it performed and what it took to get there. Buyers want to understand the revenue it generated, the costs of running it, and its contribution to earnings. A longer history gives them more to work with. A recent expansion can still be part of the discussion, provided you are clear about how much of its performance is established. Buyers pay particular attention to EBITDA, or earnings before interest, taxes, depreciation, and amortization. As revenue grows, they want to see what remains after the additional staffing and operating costs. That helps them evaluate whether expansion is improving earnings and whether the improvement can continue. That is also how to approach the forecast. Explain what the next stage requires and connect the assumptions to your actual experience. If an existing location took time to reach its current performance, account for that in the plan for another one. Buyers will have questions, and an owner who knows the economics can give them a much more useful answer than a growth target alone provides. → Related: How to Prepare Your Behavioral Health Business for Sale in 2026 Make sure the operation can support the next stage Another office adds work throughout the practice. HR has more people to support, billing has more activity to manage, and the systems that worked for a smaller organization may need attention. Before expanding, look at what the existing team can handle and where additional investment will be required. Staffing is a good place to start. Too much administrative expense can consume the earnings growth was supposed to create. Too little capacity can leave people stretched and make hiring or retention harder. The right answer depends on your practice, its services, and the work that needs to get done. It takes regular attention to the numbers to know where you stand. Service mix deserves the same review. Understand what each service contributes, what resources it requires, and how it fits the practice. There may be opportunities to improve the mix, but each decision needs a clinical and business rationale. Adding services simply to make the business look broader can create more complexity than value. Reviewing financial performance every month helps you see whether growth is producing the expected earnings and where additional operating support is needed. It gives you time to adjust the expansion plan while those decisions can still make a difference. Give the team room to lead As the practice gets larger, an owner can become the limiting factor without intending to. If every staffing question, operating decision, and financial issue comes back to you, expansion keeps adding to your own workload. A buyer will want to understand how that arrangement would work through an ownership transition. Before adding another location, be clear about who will handle the additional operating decisions and whether the existing team has the capacity. If those responsibilities keep returning to you, the expansion plan needs to account for that extra work. Turnover affects expansion capacity, too. Hiring and retaining the people needed to deliver care and manage the larger operation has to be part of how you plan the expansion. Look at whether workload or compensation is making that harder before taking on more volume. Build the plan around your payer economics Some limits to growth come from the market in which you operate. Strong demand does not change the rates a payer will reimburse. Before committing to additional volume, understand whether the revenue will support the staffing and other costs required to deliver it. Payer concentration can also make growth more vulnerable to a disruption. If a major payer stops payments while reviewing a billing issue, the effect on a smaller practice can be significant. Sound billing practices and clinical documentation belong in the growth plan because they help support the revenue the business depends on. For an owner considering a future sale, the most useful next step is to examine the practice you have today. Look at what previous growth has produced, where the team needs support, and which assumptions the next expansion depends on. That work helps you make better operating decisions now and gives buyers something concrete to evaluate later. Key Takeaways Demonstrated revenue and EBITDA growth provide stronger evidence than a forecast alone. Staffing, service mix, and back-office capacity need to support the economics of expansion. Leadership beyond the founder and staff retention help make growth sustainable. Payer economics, billing and clinical documentation belong in the growth assessment. We can help you understand how buyers are likely to view those strengths and where preparation could make a difference. If you are thinking about the next stage for your mental health practice, we would be glad to have a confidential conversation. → Related: Selling the Practice You Built
- Preparing Behavioral Health Financials for a Quality of Earnings Review
By Kevin Taggart, CM&AP, Managing Partner, Mertz Taggart At a Glance Buyers and quality of earnings firms examine how a behavioral health business earns its money, whether the records support reported earnings, and whether those earnings can continue. Consistent reporting, documented adjustments and operating context make the financial story easier to evaluate. Preparation should begin before buyers rely on the earnings figure in an offer. When a buyer makes an offer, the number behind it depends on your earnings, and a quality of earnings review is how that number gets tested. A firm hired by the buyer examines the earnings, the records supporting them, and how well they reflect the ongoing business. Questions that seemed straightforward while you were running the practice can become more involved when an offer depends on the answer. As an owner, you know the decisions behind your financial results, why staffing costs changed, which expenses were unusual, and what drove a stronger month. Some of that knowledge may live in the financial records; some may live mostly with you and the people who help run the business. Preparing before you are in the middle of a transaction gives your team a stronger basis for the review that follows.The review examines the earnings, the records supporting them, and how well they reflect the ongoing business. Consistent reporting and well-supported explanations give your team a stronger basis for defending the value being negotiated. Make it possible to compare one period with the next Buyers generally want to examine at least two years, plus current YTD of financial results, and sometimes three. They are looking at how the business has changed over time. To do that, they need reporting that lets them compare the same categories across those periods. If an expense appears in one category this year and another category next year, the reviewer has to work out what happened before assessing performance. There may be a perfectly reasonable explanation. Keep it with the records so your accountant and transaction team can answer the question without reconstructing it months later. Someone on your team needs to be responsible for the financial records and available to explain the calculation to your accountant, advisor, and the buyer's reviewers. → Related: How to Prepare Your Behavioral Health Business for Sale in 2026 Be ready to explain each EBITDA adjustment Adjusted EBITDA is intended to reflect the business's normalized earnings before interest, taxes, depreciation, and amortization. The calculation may remove certain owner-related or one-time expenses that are not expected to continue after a sale. Those adjustments, commonly called add-backs, can affect the earnings figure used to negotiate the purchase price. An adjustment needs documentation for both the amount and the reason it belongs in the calculation. What was the expense? When did it occur? Why would removing it give a more accurate view of ongoing earnings? Your accountant and advisor should be able to work through those questions before a buyer's QoE team raises them. If the explanation depends on an assumption about the operation after closing, make that clear. Reviewers may reach different conclusions about an adjustment, and calling a cost nonrecurring will not resolve the discussion on its own. The underlying records and a reasonable explanation are what give your team a basis for the conversation. The same thinking applies when recent earnings have improved. Connect the change to what happened in the business. A staffing decision or an operating improvement may help explain the result, but the buyer still needs to understand whether the benefit can continue. Organizing that documentation early puts you in a better position to address the question. Connect the financials to the way the practice earns revenue The earnings have to make sense alongside the operation. In a behavioral health practice, services are provided, documented, billed, and ultimately paid for. Questions about clinical documentation or billing can therefore become questions about the revenue a buyer is relying on. Revenue that depends heavily on one payer or on grants may need additional support. Explain the concentration, any known collection issue, and the history behind grant revenue, including relationships that depend on the owner. If an audit, licensing concern, or accreditation issue could affect earnings, work with the appropriate specialists and your transaction team to establish the financial implications. Keep the earnings support current The earnings calculation needs to stay connected to the business as the transaction moves forward. Keep current results alongside the periods already presented so your team can explain whether recent performance supports the earnings a buyer is evaluating. If performance changes during the sale process, work with your advisor to explain the difference and provide the relevant records. A change in staffing, costs, or collections may require a fresh look at the earnings calculation. The buyer needs to understand its effect on the ongoing business. Before going to market, review the earnings calculation with your accountant and advisor. Separate adjustments you can already support from those that need more records or depend on an unresolved assumption. That gives the review a clear purpose and shows where more preparation is needed. Key Takeaways Keep financial categories consistent and explain material changes across periods. Document each proposed EBITDA adjustment and the reason it reflects ongoing earnings. Explain payer concentration, grant revenue and known issues that could affect collections. Update the earnings support as current results change during the sale process. If you are considering a sale of your behavioral health business, I’d be glad to talk through where that preparation should begin. → Related: What Actually Happens During Healthcare M&A Due Diligence
- The Resurgence of Private Duty Home Care M&A
By Cory Mertz, Managing Partner, Mertz Taggart At a Glance Private duty home care M&A is picking up after a quiet two years. Buyer interest is returning, platforms are receiving new capital, and the regulatory environment around government-funded care is pushing some acquirers toward private-pay alternatives. For owners of non-medical home care agencies funded by private pay or LTC insurance, the market is more receptive than it has been in some time. The fundamentals still drive outcomes, but a broader buyer pool gives sellers more options on price, structure, and what comes next. Private duty home care M&A is beginning a resurgence. Over the past three months, we have heard from more buyers asking about private duty home care opportunities—or making sure we still have them on our radar—than we did in the previous two years. Some are new to us. Others are established buyers renewing their interest. That is a meaningful change in the conversations we are having. The interest is backed by investment in established platforms and continued acquisitions of local agencies. For owners who have been waiting for a more receptive market, the change is worth paying attention to. Government-funded home-based care transactions have become harder to underwrite and close. Buyers still need to grow, and private duty home care offers a path without direct dependence on government reimbursement. What We Mean by Private Duty Home Care Private duty home care is non-medical care funded by private pay or LTC insurance. It includes companionship, meal preparation, transportation, medication reminders, and assistance with activities of daily living. It does not include Medicaid-funded personal care or VA-funded services. It is also different from private duty nursing, which involves skilled nursing care delivered in the home. A private duty agency has plenty of operating challenges: caregiver recruiting and retention, wage pressure, scheduling, client turnover, and local management. But it does not face the same government rate-setting, enrollment, billing-review, or repayment exposure that buyers must evaluate in Medicare- and Medicaid-funded businesses. That difference is becoming more valuable. Recent Investments Show Where Buyers Are Looking The past 12 months have brought a series of investments in home care platforms—from healthcare-focused sponsors and franchise investors to international operators. Frontline Healthcare Partners acquired Integracare, a Canada-based private-pay home care provider, in October 2025. NexPhase Capital invested in Always Best Care the following month. In January 2026, Main Post Partners acquired HomeWell Care Services. A month later, Dovida entered the U.S. through its acquisition of A Place at Home. General Atlantic’s reported $3 billion acquisition of TEAM Services Group, a diversified home care and household employment platform with private-pay operations. Warburg Pincus also invested in Cornerstone Caregiving, a national non-medical home care provider serving both private duty and VA-funded clients.. The acquisitions are happening at the local level, too. Avenues Home Care acquired Alabama-based As Close As Family in October 2025, an example of the expansion these platforms are pursuing. Some of these platforms operate across multiple payer or service lines. The common thread is investment in home care businesses with private duty exposure, not an exclusive focus on private-pay providers. For an agency owner, the significance goes beyond the announcements. A platform investment puts capital, management resources, and acquisition capacity behind a business. Your agency may provide the geographic coverage, caregivers, referral relationships, or leadership team that buyer needs next. Government Scrutiny Is Changing the Calculation The private duty investment case predates the current fraud crackdown. But the environment around government-funded healthcare has made the comparison more compelling. In May 2026, CMS imposed nationwide Medicare enrollment moratoria on new home health agencies and hospices, including certain changes in majority ownership. The agency also announced expanded investigations, enrollment screening, site visits, and claims reviews. Medicaid enforcement has intensified as well. CMS reported that the first 88 days of its Medicaid Fraud War Room produced federal or state enforcement activity involving 50 high-risk providers and more than $203 million of Medicaid payments. In a transaction, that environment means more attention to billing practices, eligibility documentation, payer contracts, enrollment history, and potential repayment exposure. Medicaid adds state-specific requirements that can affect transaction structure and closing. We are seeing how difficult it can be to get government-funded deals across the finish line, even when the underlying business is attractive. Buyers with both government-funded and private duty operations have a choice about where to deploy acquisition capital. Private duty allows them to add clients, caregivers, referral relationships, and cash flow without taking on the same reimbursement uncertainty. What Buyers See in Your Agency For owners of private duty platforms, the expanding buyer universe is particularly significant. Buyers looking to enter the sector or establish a regional presence will pay a premium for a business that already has the management team, operating infrastructure, and scale to support further growth. They are acquiring both current earnings and the ability to build on them. Established local agencies can also benefit. A buyer may value your agency for its market position, caregiver base, referral relationships, or the density it adds to an existing footprint. The value depends on what you have built—and what it allows the buyer to do next. That is why the buyer’s strategy matters as much as the headline multiple. A competitive process helps identify who sees the greatest value in your business and gives them a reason to pay for it. Nova Leap Provides a Public-Market Perspective Nova Leap Health is a Canadian company headquartered in Halifax, trading on the TSX Venture Exchange under NLH and on the U.S. OTCQX market under NVLPF. It has built much of its U.S. home care business through acquisitions, with U.S. operations accounting for approximately three-quarters of revenue in the first half of 2026. In our view, Nova Leap is the closest public-market comparable for private duty home care. Its focus on acquiring and operating local home care agencies makes it particularly relevant to owners considering a sale. The company’s share price increased approximately 82% between year-end 2025 and September 30, 2026. It also reported record Q2 results, with revenue increasing 17.1% and Adjusted EBITDA increasing 65.2% from the prior-year quarter. As of September 30, Nova Leap had an enterprise value of approximately US$34.3 million, representing roughly 13.2x its US$2.6 million of trailing-12-month Adjusted EBITDA through June 30, 2026. What This Means if You Are Considering a Sale A broader buyer market can give you more choices—not just on price, but on your role after closing, the future of your team, and how the business continues to grow. The fundamentals still determine the outcome. Buyers want reliable financials, defensible margins, stable client relationships, and a business that can operate after the owner steps away. Those qualities become more valuable when several credible buyers are competing for them. If you have thought about selling but assumed the market was too quiet, this is a good time to revisit that assumption. The freeze is beginning to thaw. We are hearing directly from buyers, investors are committing capital, and platforms are expanding. If you own a private duty home care agency, and are curious about how it would be viewed in the current private duty M&A marketplace, we’ll be happy to have a discussion. Key Takeaways Buyer interest in private duty home care has increased noticeably over the past three months, after a relatively inactive two-year period. Recent investments by sponsors including NexPhase Capital, Main Post Partners, and General Atlantic reflect a broader capital commitment to home care platforms with private-pay exposure. Government enforcement activity, including CMS moratoria on new Medicare home health and hospice enrollments and expanded Medicaid fraud investigations, is making government-funded deals more complex to underwrite and close. Private duty home care avoids the reimbursement rate-setting, billing review, and repayment exposure that buyers must evaluate in Medicare- and Medicaid-funded businesses, which is part of what makes it more attractive now. Nova Leap Health, a public-market comparable for private duty home care, saw its share price increase approximately 82% between year-end 2025 and September 30, 2026, alongside record Q2 revenue and EBITDA results. Buyers are looking for agencies with reliable financials, defensible margins, stable client relationships, and operational infrastructure that can support growth after the owner exits. A competitive sale process helps identify which buyers place the highest value on a specific agency and gives them a reason to pay for it.
- Behind the Curtain: What Hospice Owners Should Know About the Strategic Buyer's Process
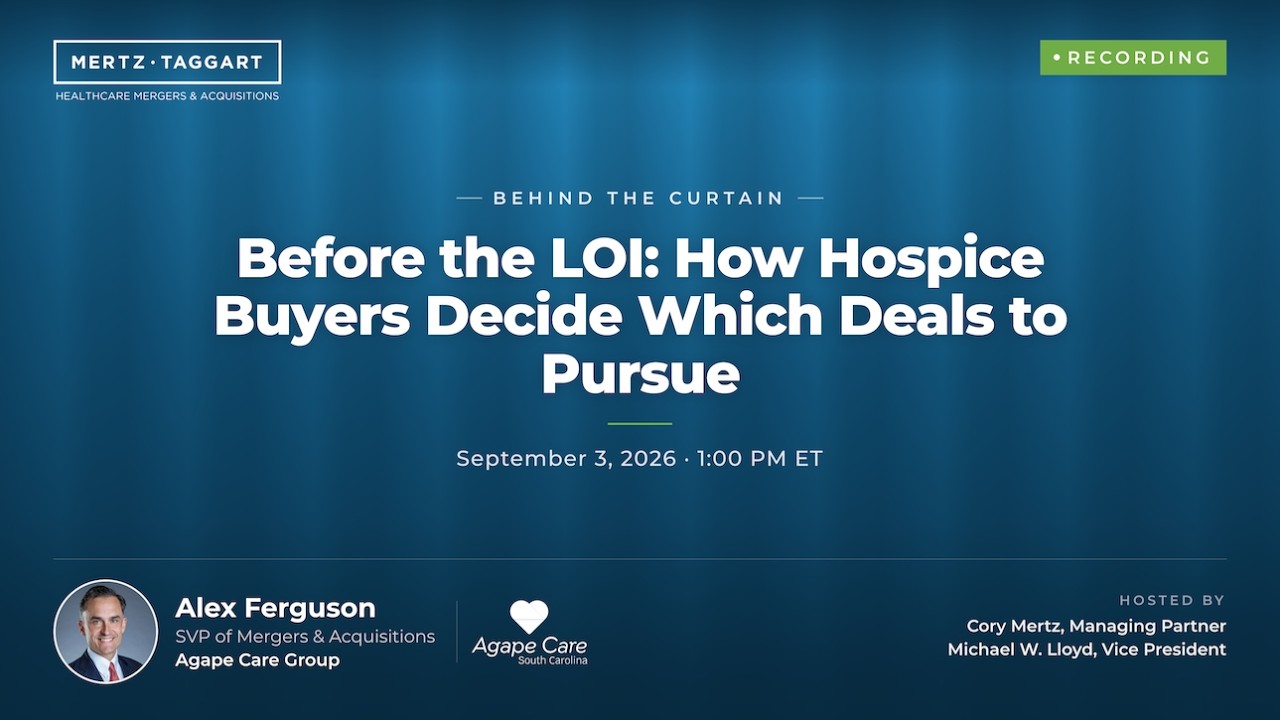
By Mertz Taggart | Featuring insights from Alex Ferguson, Senior Vice President of Mergers and Acquisitions, Agape Care Group | September 2026 At a Glance A hospice buyer’s offer is a statement about risk, not just earnings. Before an IOI (Indication of Interest) buyers want the owner’s story and no surprises on CAP, audits, or the 36-month rule, and culture and clinical quality decide whether an agency is considered for a top-tier multiple at all. Sellers hold maximum leverage until the LOI (Letter of Intent) is signed, which is why Mertz Taggart works to get every issue surfaced and addressed before that point. Most hospice owners will sell a business once. Buyers do it every month, which means the two sides come to the table with very different visibility into what happens next. Our Behind the Curtain webinar series exists to close that gap. On September 3, Cory Mertz and Michael Lloyd hosted Alex Ferguson, Senior Vice President of Mergers and Acquisitions at Agape Care Group, a hospice operating company that has grown from 3 states to 11 and completed about 20 acquisitions since 2022. We asked Alex to take owners inside a strategic buyer’s process, from the first teaser through the letter of intent. That is the stretch of a deal where a seller holds the most leverage, and where an owner’s decisions carry the most weight. What follows is what we took away from the conversation, and what it means for an owner preparing to sell. What is a buyer actually pricing when they set the multiple? The multiple is a measure of risk. It reflects how confident a buyer is that the cash flow they are inheriting will still be there after closing, which is why two agencies with similar revenue and EBITDA can command very different multiples. Owners tend to think of the multiple as a market rate, something that trades in a tight range. In our experience it is closer to a confidence score. Transition risk and sustainability risk sit at the center of it, and payer mix, referral diversity, management depth, growth trajectory, and margin profile all move it. So does the competitive leverage an advisor brings to the table. Alex confirmed it from the buyer’s side. There is no black box. Agape has paid what he called an “infinity multiple” for a business that was close to break-even, because the culture, clinical quality, and trajectory gave the team high confidence in where it was headed. And before Agape will consider a top-tier range at all, an opportunity has to clear two gates: culture and clinical quality. If either one is weak, the numbers do not rescue it. For an owner, the implication is that the work of earning a strong multiple happens long before a buyer sees the financials. It is done in the referral relationships, the management team, and the clinical record a buyer will read as a proxy for risk. → Related: Maximizing Value: How Advisors Evaluate Home Health & Hospice Assets What should an owner have ready before buyers see the teaser and CIM? A clear story and clean data. Buyers can size up a hospice’s metrics in a matter of days. What takes longer, and what they weigh most heavily, is whether the story behind the numbers holds together. Why is the owner selling, and why now? Is this a quick flip, or a business someone built over decades? Is there a team that can carry the culture forward, or does everything depend on one person walking in at 8 AM? A good advisor knows those answers before the first buyer call, because the first thing an experienced buyer does after reading the materials is call the advisor and ask what is really going on. On the data side, the early checks are predictable: CAP exposure, PEPPER reports, referral source diversification, audit history, and whether the deal can clear the 36-month rule. Alex’s advice to sellers on all of it was blunt. Come clean now. Buyers do not like surprises, advisors do not like surprises, and an issue disclosed early can be planned around. The same issue discovered in diligence becomes a negotiation. What happens inside the buyer’s process before an indication of interest? Inside a strategic buyer’s evaluation, an opportunity gets reduced to one page and one question: does this feel like a fit, and how hard do we want to run after it? Agape’s deal team distills the history, the reason for selling, KPIs, and the P&L into a one-pager, with upside on one side and open diligence questions on the other, then huddles with the executive team. Every opportunity has entries in both columns. What the owner controls is the ratio. Our job as the advisor in that window is to make sure the upside column is complete and well supported, and that nothing lands in the diligence column we did not already know about. Then we stack the IOIs. In a well-run competitive process there will be several, and the spread between them can be wider than owners expect. → Related: If a Buyer Approaches You Directly, a Competitive Process Will Almost Always Get You More Money How should an owner approach the management meeting? The management meeting runs in both directions. The buyer is testing whether the seller will be straightforward once the deal is under LOI, and the seller is deciding whether this is the right long-term home for the business. Once a buyer crosses the IOI threshold, they are spending real money and flying senior people in to sit across from the owner, so they arrive prepared. A buyer like Agape will ask for a short call with management beforehand and for as much data as possible in advance: patient days, admissions, blinded referral sources, diagnosis mix. In the room, the questions are about people. A hospice is its clinicians and the team supporting them, so buyers want to know how the agency attracts and retains staff, and how the culture will hold up after a transition. They also want the warts. As Alex put it, if the lead salesperson gives notice, will the owner bring the news and a plan? That is a seller a buyer can work with. The owners who come out of these meetings in the strongest position are the ones who ask hard questions back. What does integration look like? Where will my people land, and how will they be treated? Can I talk to owners who have already sold to you? Buyers read those questions as a sign the seller is proud of what they built, not as an obstacle. In Alex’s words, everybody lives in choice, and the buyer has to earn the right to keep the deal alive at every step. Why does the window between the management meeting and the LOI matter so much? Sellers hold maximum leverage right up to the moment they sign a letter of intent and grant exclusivity. Everything that can be resolved before that signature should be. In the two to three weeks before an LOI deadline, a serious buyer does confirmatory diligence at its own expense: a request for the full data set, a look at quality indicators such as PEPPER reports, CAHPS scores, and HOPE data. The goal is conviction. When a buyer submits an LOI, we want the number in it to be one they have already pressure-tested, so it holds through closing. Our philosophy matches the buyer’s here. More information pre-LOI is better, with clear exceptions. Trade secrets, patient information, employee information, and referral source detail stay protected until the deal is under LOI and the buyer has earned that access. Nearly everything else is fair game, and the more comfort a buyer has before signing, the more confidence an owner can have that the deal will close on the terms they agreed to. Michael noted that this is where we earn our role as intermediary. A strong buyer will usually ask for more than a client is comfortable sharing early. Our job is to give the buyer enough to reach a premium valuation and full conviction, while protecting the company in the market. How can a seller tell whether a buyer will actually close? Deal certainty has two parts, whether the buyer can close and whether they will. The first is easy to verify, and the second shows up in behavior. By the time a buyer is at the LOI stage of one of our processes, we know they can close. Their financial sponsor and funding are typically a matter of record. What owners worry about is intent, and the signals there are consistent: responsiveness, thoughtfulness when a problem surfaces, and visible spending of time and money on the project. A buyer who goes quiet or stops pursuing the deal consistently is telling you something, even if nobody says it out loud. Alex’s example of how a good buyer handles a post-LOI surprise is worth keeping. Suppose diligence turns up a hypothetical $250,000 CAP liability. His approach is to call the advisor before anything is papered, flag the quality of earnings impact, and propose walling it off in a special indemnity bucket rather than cutting the enterprise value. A buyer who retrades a deal, in his words, is a buyer who will not get the next one. There is a structural reason to expect that behavior from serious buyers. Once the LOI is signed, the buyer starts paying for clinical compliance work, a quality of earnings review, and legal drafting, and every dollar spent increases their own incentive to get to close. It is also why we stay engaged after the LOI rather than stepping back. Getting a deal to closing as quickly as possible, with minimal surprises, is the third part of our job, not the end of it. What should an owner expect after closing? The businesses buyers pay the most for are the ones they intend to keep intact, which is why questions about integration, the brand, and the owner’s own role are worth asking early. Agape’s guiding principle after closing is to retain everyone who wants to stay, and it runs a dedicated integration team whose sole job is that transition, starting with one-on-one conversations with every employee. Not every buyer works that way. Some assemble an integration team from good people with other day jobs, and the difference shows up in retention. It is a fair thing to ask any buyer about. On the brand, most Agape branches now operate under the ACG name, and an acquired agency may migrate over time. On the owner’s role, most sellers we work with are ready for whatever comes next, whether that is retirement, family, or another project, and buyers have latitude to accommodate that. The typical ask is to help preserve the culture and stay reachable. Owners who want to stay through the next chapter can have that conversation too. Either way, it is part of the discussion when we take a company to market, not an afterthought. What should an owner two to three years out do now? Run the business as if it will never be sold, and check in on it with an advisor once or twice a year. That was Alex’s advice, and it matches how we work with owners years ahead of a transaction. Most operators are heads down, doing good work and rarely pausing to articulate it. A buyer, though, wants to hear the narrative and see the data that supports it, and the owner who can connect the two walks into the process with a clear advantage. Structured time with an advisor, on a quarterly or semiannual rhythm, is where blind spots and weak spots get identified while there is still time to address them. It is also where strengths get documented in a way a buyer can verify. The businesses a strategic buyer most wants are the ones that have been doing the right things for patients and employees all along, because that is where the clinical quality, the culture, and the economics tend to line up. → Related: Your Company Might Be Great. That Doesn’t Mean It’s Valuable. Questions owners asked Can two hospices combine under a holding company to command a higher multiple? Rarely in a way that pays off. Two agencies bring two cultures, two care models, and often two EMRs with no shared platform, and buyers do not see that supporting an extra half turn or full turn. Alex’s read was that the juice is seldom worth the squeeze, though two like-minded operators who both clear the culture and quality bar have effectively vetted each other. If two companies truly integrate into one operation, a somewhat higher multiple is possible, but the work and risk involved are significant. How can a seller protect confidential information during a process? Share information in stages, and be deliberate about which buyer sees what, and when. Referral sources, employee detail, and trade secrets do not need to be shared early, and much of it can be de-identified as Facility A, B, and C. That staging is part of what we manage for clients. Alex added a practical test: check the buyer’s track record. A group that has never done a deal and is asking detailed questions about referral sources is telling you something. Does it matter whether the agency is a C corporation or an S corporation? Yes. Buyers generally prefer not to hold assets in a C corporation, and the seller of one faces double taxation that the buyer expects the seller to bear. Converting to an S corporation requires a seasoning period before the full benefit applies, so this is a conversation to have with an advisor and a tax professional years ahead of a transaction, not months. Have someone run the math. The valuation premium a buyer might pay for a C corporation rarely makes up the difference. Are hospice deals structured as asset or stock purchases? Mostly stock, on Agape’s side and in what we have seen across the market over the past couple of years. Alex explained the “our watch, your watch” construct: the buyer takes responsibility for the entity after closing, the seller remains responsible for activity before it, and the indemnity escrow and purchase agreement are structured so that a tax clawback or audit tied to a prior period lands where it would have if the owner had never sold. Do buyers value a hospice on a per-ADC basis? No. Value rests on the cash flow today and the cash flow the buyer is inheriting, with culture and clinical quality driving confidence in both. A per-patient number can be derived from an offer by dividing it by average daily census, but it is an output, not an input, and neither Agape nor Mertz Taggart treats it as a way to value a hospice. Is the current moratorium pushing hospice valuations higher? Not in Alex’s view, even though it limits de novo growth and puts more weight on organic growth and quality M&A. The reason is scrutiny. Audit activity is up, surveys are up, and more states are under a provisional period of enhanced oversight, so buyers have to be careful about who they acquire, indemnifications or not. Key Takeaways The multiple is a measure of risk, not a market rate. Culture and clinical quality are the gates buyers check first. Surface every issue early. An item disclosed before the IOI can be planned around; one found in diligence becomes a negotiation. Use the management meeting both ways. Buyers read hard questions about integration and people as a sign of a seller worth pursuing. Sellers hold maximum leverage until the LOI is signed. Resolve what can be resolved before granting exclusivity. Deal certainty shows up in behavior: responsiveness, problem-solving, and money spent, and it grows after the LOI as the buyer invests. Owners a few years out should run the business as if it will never be sold, and review it with an advisor once or twice a year. Every buyer sees your agency a little differently Every buyer runs a slightly different process, with its own hot-button issues. The more an owner understands how buyers evaluate an agency, the better prepared they can be when the time comes, and the more leverage they carry into the process. If you own a hospice agency and want to know how the buyer universe would see it today, we would welcome a confidential conversation. Mertz Taggart has advised healthcare services owners for over twenty years, through hundreds of transactions.
- Michael Lloyd Promoted to Vice President at Mertz Taggart
By Mertz Taggart Michael Lloyd has been promoted to Vice President at Mertz Taggart, reflecting his expanding leadership role within the firm’s home-based care practice. Over the past year, Michael has taken on greater responsibility across Mertz Taggart’s sell-side engagements, with a particular focus on deal execution. He works closely with clients throughout the transaction process and has increasingly led buyer conversations, management meetings, and other critical components of active engagements. “Michael has earned this,” said Cory Mertz, Managing Partner and co-founder of Mertz Taggart. “He has taken on a much larger role with our clients and our deals, and he brings the judgment, responsiveness and follow-through that this work requires. When we have a complicated process or a client that needs us to stay close to the details, Michael is someone I know we can count on.” Michael joined Mertz Taggart in 2022 as lead M&A Associate in the Home Care Division, bringing a background that is relatively uncommon in M&A advisory. His career began as a Patient Care Representative with a large national provider, where he developed a working understanding of how home care agencies operate day to day. From there, he moved to the vendor side of the industry as the first employee of a start-up data company that applied CMS data to help agencies track growth and improve patient outcomes. Before joining us, Michael provided clinical and financial services at an industry-leading consulting firm. The range of those roles gives him a perspective across the operational, clinical, and financial dimensions of the home health and hospice market. “I’ve had the opportunity to work with a lot of great owners and teams over the last several years, and I’ve learned something from every process,” Lloyd said. “Selling a healthcare business is a major decision, and there are a lot of moving pieces between deciding to move forward and getting a deal closed. I’m looking forward to continuing to take on more responsibility and helping our clients through that process.” Michael earned his bachelor’s degree in finance from Elon University’s Martha and Spencer Love School of Business. “Michael has already been operating at a higher level,” Mertz added. “This promotion makes that official, and I’m excited to see where he takes it from here.”
- You’re Running a Better Business on EOS®. Is It Becoming a More Valuable One?
By Cory Mertz, M&AMI, Managing Partner, Mertz Taggart At a Glance Companies running on EOS® are often already working on the things that make a business more attractive to a buyer, including stronger management, clearer accountability, and less owner dependence. A better-run business and a more valuable business are not the same thing, though. The question worth asking is which of the things you’re working on are actually moving enterprise value. Running a Better Business Is Not Quite the Same as Building a More Valuable One Through our Value Accelerator Program, we have been working with a number of owners recently, including some who run their companies on EOS, and those conversations keep reinforcing the same point: a lot of the things that make a company easier to run also make it easier to sell. A strong management team, documented processes, clear accountability, and an owner who is out of the middle of every decision all matter. If you run on EOS, none of that will sound particularly new. Buyers, though, are looking at those things through a different lens. They are not asking whether the company runs good meetings or whether everyone has a clear seat on the Accountability Chart. They are asking a much more basic question: how confident am I that this cash flow will still be here after the transaction? That question ultimately drives much of the valuation conversation. A Multiple Is Really a Conversation About Risk Owners tend to focus on the multiple, which is understandable, since it is the number everyone hears about. A friend sold for six times, someone at a conference heard home care agencies are trading at seven, and a buyer tells an owner they can pay five. The problem is that a multiple without context is not particularly useful. When we value a business, we first look at the range a company like that could reasonably trade within, based on size, the type of business, buyer demand, and the state of the market. The harder question is where this particular company belongs within that range, and answering it comes down to two broad categories of risk. Transferability: What Happens When Ownership Changes? Transferability is about what happens when ownership changes hands. If the owner is personally responsible for most of the important relationships, decisions, and revenue generation, there is risk in transferring that business to somebody else, and the same is true if there is no management layer underneath the owner or if key processes live in people’s heads instead of in the business. A buyer has to ask what falls apart when this person leaves. Sustainability: What Happens Twelve Months Later? Sustainability assumes the business transfers successfully, then asks what happens twelve months later. Is revenue heavily concentrated with one payer, customer, or referral source? Is one employee responsible for a disproportionate amount of growth? Is reimbursement exposed to a meaningful regulatory change? Are recent earnings sustainable? That is a different set of risks, though buyers care about both, and it is why two companies with the same revenue and EBITDA can have very different values. → Related: What Behavioral Health Owners Should Understand Before Comparing Offers Revenue, Margin and Multiple Give You Three Places to Work At a high level, enterprise value comes down to three variables: Revenue × Margin = EBITDA EBITDA × Multiple = Enterprise Value That sounds obvious on its own. What is more useful is applying it to the gap between what a business is worth today and what the owner ultimately needs it to be worth. Suppose a business is worth $8 million today and the owner needs it to be worth $15 million before a transaction makes sense. Saying, “We need to create another $7 million of value,” doesn’t give the management team much to work with. Break it apart, though, and there is something to work on. How much could realistically come from revenue growth? Does the margin need to improve, or is it already where it should be? What is keeping the company from trading toward the upper end of its potential multiple range? Importantly, those three variables can interact. Growth can do more than increase revenue, since a larger company may also command a stronger multiple. Improving margin can help, but not if the margin is artificially high because the company has underinvested in management or infrastructure. Reducing owner dependence may not change EBITDA at all this quarter, but it may reduce a meaningful source of transferability risk. That is why it rarely makes sense to manage each of these numbers in isolation. This Is Where EOS Can Be Especially Useful Once we understand the value gap, our framework is straightforward: Gap → Obstacles → Strategies → Actions That framework connects naturally to EOS. If an owner already runs on EOS, there is no need to invent another operating system for executing the plan. The obstacle may already belong on the Issues List, the strategy may lead to a Rock, and a metric that tells us whether the gap is closing may belong on the Scorecard. The company already has a cadence for deciding what matters, assigning ownership, and following through. The Value Accelerator adds a different question to that process: how much does this issue matter to enterprise value? Not every Issue is equally important from that standpoint, not every Rock moves the value of the company by the same amount, and something that feels urgent operationally may not be the thing creating the biggest gap between today’s value and the owner’s eventual goal. That is the piece worth understanding. Sometimes the Answer Is: Keep Doing What You’re Doing In one recent Value Accelerator engagement, the owner already had a strong EOS plan in place. We went through the valuation, looked at where the business is today and where she ultimately wants it to be, then broke down the gap. Her margin was roughly where it needed to be, the infrastructure was strong, and the company was not heavily dependent on her. There were a few risks we identified, including some concentration issues, but nothing that required us to completely rethink the business. The biggest lever was growth, and she already had the growth plan. It was in EOS, the targets were there, and the company was executing against them. Our advice was not particularly dramatic: keep doing what you’re doing. What changed is that we could put context around why. We could show how reaching the revenue target might affect EBITDA, why additional scale could also influence the multiple, and which risks were worth watching along the way. We could also connect the company’s operating plan to the owner’s financial objective, which is valuable even when the answer is not that you need to change everything. The Goal Is Not to Create More Rocks This is probably worth saying explicitly: the purpose of looking at a company through an enterprise-value lens is not to manufacture more work for a leadership team that already has plenty of it. The goal is prioritization. If you have ten Issues, which two or three could materially change what a buyer sees? Which Rocks directly address the biggest value gap? If the 10-Year Target is $30 million in revenue, do you know what a $30 million company might actually be worth, and is that enough to accomplish what you personally want from the business? Those are different questions than the ones most operating systems are designed to answer, and they are worth asking while you still have time to do something with the answers. Know Your Number Before You Need Your Number Most owners do not wake up one morning eager to start an M&A process; usually something changes first. Burnout catches up with them, a health issue comes up, a partner wants out, the reimbursement environment changes, a buyer makes an unsolicited offer, or they simply reach the point where they are ready for something different. That is a difficult time to discover the business is three years away from being where you need it to be. If you run on EOS, you already have a disciplined way to work on the business over time, and the opportunity is to make sure some of that work is also building toward the outcome you eventually want as an owner. You do not have to be ready to sell; in fact, that is really the point. Be ready before you’re ready. Know your number, know the gap, and know the path. → Related: How to Sell Your Home Care Agency: 3 Proven Exit Strategies from Private Equity Key Takeaways A better-run company and a more valuable company have significant overlap, but they are not necessarily the same thing. Enterprise value ultimately comes back to revenue, margin, and the multiple applied to earnings. The multiple is largely a reflection of risk, including how transferable and sustainable the company’s cash flow is. Companies running on EOS may already have the operating discipline required to address many of the issues that influence value. The important question is not whether you have Issues and Rocks but whether the ones you’re prioritizing are moving the business toward the value you ultimately need. Understanding that relationship years before a transaction gives you more options than discovering it once a sale process has already begun. If you’re curious how your current operating plan translates into enterprise value, a confidential valuation conversation is a reasonable place to start. Mertz Taggart has spent over twenty years advising healthcare services owners through hundreds of transactions. Sometimes a valuation exposes a meaningful gap, and sometimes it confirms you’re already doing exactly what you should be doing. Either answer is useful. Mertz Taggart is not affiliated with, endorsed by or sponsored by EOS Worldwide, LLC. EOS®, Accountability Chart®, Rocks™, Scorecard™ and related marks are trademarks of EOS Worldwide, LLC.
- AccentCare and Seasons Hospice & Palliative Care Complete Merger
DALLAS–(BUSINESS WIRE)–December 22, 2020 — Dallas-based AccentCare and Rosemont, Illinois-based Seasons Hospice & Palliative Care (Seasons), along with Advent International, the private equity sponsor of AccentCare, announced today they have finalized an agreement to combine their two organizations to better meet the growing needs for their services. The duo announced the intent to merge last month, and plan to move forward with a thoughtful integration now that the merger is complete. Providing the full continuum of post-acute care as a unified organization will simplify the complexity that comes with navigating multiple companies, benefiting physicians, payors, and patients alike. Above all, both organizations remain dedicated to providing great service and enhancing capabilities health system and other strategic partners can rely on to ensure quality care for their patients. Read the full press release press release here.
- Home-Based Care Public Company Roundup Q2 2026
Mertz Taggart follows the publicly traded home-based care companies and reports on their earnings calls each quarter. As a group, public company performance and share price serve as a proxy for industry performance and investor sentiment, respectively. Historically seen as the “ultimate consolidators”, the publicly traded home-based care trading multiples have a downstream effect on lower middle market home-based care M&A. Addus Homecare (Nasdaq: ADUS) Highlights Addus posted revenue of $377.4 million for the quarter, up 8.0% from Q2 2025. Net income was $27.6 million compared with $22.1 million, in the prior year quarter. Adjusted EBITDA rose 11.9% to $49.2 million, with adjusted EBITDA margin of 13.0% compared with 12.6% in the prior year quarter. Growth was led by the Personal Care segment, which represents 78.4% of the business at $296.0 million and grew same-store revenue 6.8% year-over-year. Same-store hours per business day rose 2.2%, within the company’s target range of 2% to 2.5%, and same-store census increased 1.2% sequentially, with growth returning in Illinois, the company’s largest market. The Hospice segment, representing 17.0% of quarterly revenue at $64.2 million, grew same-store revenue 11.1% year-over-year, with same-store average daily census increasing 6.5% to 3,964 and a median length of stay of 24 days. Average daily census exceeded 4,000 in July. The company recorded Medicare Cap expense in its Ohio market, which is excluded from the same-store calculation, and management expects no additional cap exposure for the remainder of the year. The Home Health segment, representing 4.6% of the business at $17.2 million, saw same-store revenue decline 2.8%, an improvement from the 6.6% decline in the first quarter, with sequential gains in revenue, operating income and admissions. Key Financial Figures M&A Activity On May 1, Addus closed the acquisition of the personal care operations of HomeCourt Home Care, based in Fort Wayne, marking the company’s entry into Indiana. CFO Brian Poff said the operation is running slightly ahead of volume expectations and sits close enough to the company’s Illinois, Ohio and Michigan markets to fold under existing regional leadership. A definitive purchase agreement remains in place for a similarly sized personal care operation in the Indianapolis area, which will be combined with HomeCourt once it closes. Management pointed to a wider set of opportunities reaching the market, noting that “recently, we have begun to see an increasing number of personal care opportunities, which we will be actively pursuing.” CEO Dirk Allison said owners have become comfortable that changes to Medicaid are “not really affecting our business or our industry near as much as people thought” and are now willing to bring businesses to market. He confirmed the company is evaluating scaled assets and has held leverage low in order to act on them. Guidance Management continues to expect full-year adjusted EBITDA margin of 12% to 13% and pointed to the higher end of that range, with a step up in the fourth quarter as the hospice rate increase takes effect. Aveanna Healthcare (Nasdaq: AVAH) Highlights Aveanna reported Q2 2026 revenue of $670.5 million, a 13.7% increase over the prior year period, with year-over-year growth in all three operating divisions. Net income was $40.3 million compared with $27.0 million. Adjusted EBITDA rose 8.0% to $95.4 million. Consolidated gross margin was $218.5 million, or 32.6%, compared with 35.8% in the prior year quarter, which included approximately $9 million of non-recurring favorable items in Private Duty Services. The Private Duty Services segment, representing 83% of the business, grew 14.0% to $553.9 million, driven by a 12.3% volume increase to approximately 12.4 million hours of care and a 1.7% increase in revenue per hour to $44.62. Cost of revenue per hour rose 7.8% to $31.74, leaving spread per hour of $12.88. Segment gross margin was 28.9%. The Home Health & Hospice segment grew 14.8% to approximately $69.0 million on 10,500 total admissions and 14,700 total episodes of care, up 18.5% from the prior year quarter. Medicare revenue per episode was $3,202 and segment gross margin was 53.9%. Medical Solutions grew 9.4% to $47.5 million on approximately 95,000 unique patients served, up 4.4%. The company’s preferred payor strategy continued to advance, with three agreements signed in Private Duty Services during the quarter, bringing the total to 37 against a 2026 goal of 38. Preferred payor agreements now account for approximately 64% of total Private Duty Services MCO volumes, up from 60% at the end of the first quarter. In home health, Aveanna reached its full-year goal of 50 preferred payor agreements, while Medical Solutions ended the quarter with 20 against a goal of 25. Key Financial Figures M&A Activity Aveanna closed the acquisition of Family First Homecare, a Florida-based provider of in-home pediatric care, in early June, funding the purchase and closing costs with cash on hand. Shaner described the integration as in its front third, with the back office and EMR transitions still ahead, and expects the work to be complete late in the fourth quarter. He said the transaction strengthened the company in Florida and improved service distribution in Iowa, South Dakota and Illinois. Looking forward, Shaner said “we think the majority of our M&A activity moving forward will be in the adult space,” with home health and hospice the focus now that most Private Duty Services states are filled in. Guidance Management raised full-year 2026 guidance to revenue of greater than $2.68 billion, from a range of $2.63 billion to $2.65 billion, and adjusted EBITDA of greater than $365 million, from a range of $338 million to $342 million. The Pennant Group, Inc. (Nasdaq: PNTG) Highlights Pennant Group reported total revenue of $298.0 million for the quarter, an increase of $78.5 million or 35.8% over the prior year quarter. Adjusted EBITDA grew 48.2% to $24.3 million, or $26.1 million prior to non-controlling interests, up 51.0%. The Home Health and Hospice segment delivered revenue of $237.8 million, an increase of $71.8 million or 43.2%, with segment adjusted EBITDA of $37.7 million, up 48.2%. Same-store segment margin improved 70 basis points year-over-year. Hospice revenue grew 40.4% to $103.6 million, with admissions up 38.4% and average daily census up 40.1% to 5,477. Same-store hospice admissions grew 8.8% and same-store average daily census grew 10.8% to 4,089. The company recorded approximately $1.3 million of Medicare Cap in the quarter, approximately $0.5 million below the prior year level, with most of the exposure in California. Home health revenue grew 50.8% to $119.4 million, with total admissions up 62.3% and total Medicare admissions up 70.7%. Same-store home health admissions grew 9.7% and same-store Medicare admissions grew 13.6%. Key Financial Figures M&A Activity The transition of the home health, hospice and home care operations acquired from UnitedHealthcare in Tennessee, Alabama and Georgia is three of five waves complete, with the fourth nearing completion and the fifth, one of the largest, started August 1. Management expects the process to be finished by the middle of the fourth quarter and said margins are trending ahead of internal expectations, with volumes holding above the levels at the time of acquisition. In senior living, Pennant has completed seven acquisitions year to date. In May the company acquired the operations and real estate of Copper Canyon Memory Care, a 40-unit community in Tucson. On June 1 it assumed operations of Memory Care of Contra Costa, a 46-unit memory care community in Pleasant Hill, California, and on August 1 it acquired the operations and real estate of River Center Assisted Living, a 63-unit community in Tucson. The additions bring the company’s real estate portfolio to nine properties, five of which were acquired in the last 12 months. On June 4, Pennant announced an equity investment in Hartford HealthCare at Home, which it has managed since 2024 and serves more than 30,000 patients from nine locations in Connecticut. Guidance Management raised full-year 2026 guidance to total revenue of $1,171.1 million to $1,190.1 million, adjusted diluted earnings per share of $1.34 to $1.41 and adjusted EBITDA of $94.4 million. BrightSpring Health Services, Inc. (NASDAQ: BTSG) Highlights BrightSpring posted total revenue of $3.9 billion for the quarter, up 23.0% year-over-year, with adjusted EBITDA of $206 million, a 44% increase, and adjusted EBITDA margin of 5.3%, an 80-basis point improvement. Net income was $87 million, compared with $9 million in the prior year quarter. Results reflect continuing operations and exclude the Community Living business divested on March 30. Pharmacy Solutions grew revenue 22% to $3.4 billion, with segment adjusted EBITDA of $180 million, up 44%. Specialty and infusion revenue grew 30% to $2.9 billion on 31% script growth, driven by the branded oncology limited distribution drug portfolio, new LDD wins, wraparound fee-for-service programs and brand-to-generic conversions. The company added two ultra-narrow network LDDs in the quarter, bringing its total to 155, and has launched 12 year to date, four as exclusive partner and eight ultra-narrow. Provider Services grew revenue 30% to $466 million, with segment adjusted EBITDA of $75 million, up 33%, and a margin of 16.1%. Home Health grew 51% to $278 million on 54% average daily census growth, de novo expansion and the integration of acquired branches. The Amedisys and LHC branches contributed approximately $78 million of revenue and approximately $8 million of adjusted EBITDA in the quarter. Rehab grew 12% to $82 million and Personal Care grew 7% to $107 million. Key Financial Figures M&A Activity Management described a full pipeline, with several small tuck-ins and geographic expansions signed during the quarter and further transactions possible in the second half. Rousseau said geographically adjacent tuck-ins remain the core of the strategy, that larger transactions for BrightSpring are typically below $30 million to $40 million of EBITDA, and that the company is considering adding to its sevenperson M&A team. Integration of the acquired Amedisys and LHC branches is complete on the company’s home-based platform, and management raised the expected 2026 adjusted EBITDA contribution from those assets to approximately $35 million from approximately $30 million. Guidance Management raised full-year 2026 guidance to total revenue of $15.1 billion to $15.425 billion, including Pharmacy Solutions revenue of $13.2 billion to $13.5 billion and Provider Services revenue of $1.9 billion to $1.925 billion. Total adjusted EBITDA is now expected to be in the range of $820 million to $845 million, reflecting 32.8% to 36.8% growth over full-year 2025 excluding Community Living in both years, and includes approximately $35 million from the Amedisys and LHC branches. Option Care Health, Inc. (NASDAQ: OPCH) Highlights Option Care posted second quarter revenue of $1.4 billion, up 1.9% compared with the prior year and 7% sequentially, ahead of management’s expectations. Adjusted EBITDA of $117.5 million rose 3.0% year-over-year and 12% sequentially, and adjusted earnings per share of $0.45 increased 9.8%, including a three-cent uplift from share repurchases. GAAP net income was $53.9 million, up 6.7%, or $0.35 per diluted share. Acute therapy revenue grew in the high single digits, with sequential and year-over-year growth across all key therapeutic categories and in the number of patients served. Chronic therapy revenue was in line with the prior year and grew in the high single digits sequentially, led by the IG and neurology portfolio. In the chronic inflammatory disease portfolio, management said the company “began to stabilize our portfolio coming out of the first quarter reset and saw our second quarter patient census rise sequentially,” and expects to build census further through the year. The company continues to expect a full-year revenue headwind of approximately 600 basis points and a gross profit headwind of $55 million from that portfolio and continues to expect Stelara and related biosimilars to represent less than 1% of 2026 net revenue and gross profit. The rare and orphan portfolio grew sequentially and yearover-year, with several newly added therapies not going live until late 2026 or early 2027. Ambulatory infusion clinic utilization continued to increase, with five facilities added in the quarter, more than 190 locations now in the network and visits growing more than 20% year-over-year. The company conducted more than 35% of its nursing visits in one of its suites or clinics during the quarter and continues to add to a portfolio of more than 600 therapies. Key Financial Figures M&A Activity Capital allocation priorities begin with organic investments to drive revenue growth, capacity and cost structure optimization, followed by periodic share buybacks, with acquisitions focused on adjacencies and tuck-ins last. CFO Meenal Sethna said guidance does not include any new or prospective repurchases beyond the $150 million completed in the second quarter. Guidance Management maintained full-year net revenue guidance of $5.675 billion to $5.775 billion and narrowed adjusted EBITDA guidance to a range of $480 million to $495 million and adjusted earnings per share to $1.85 to $1.92. Operating cash flow is still expected to be at least $320 million, with net interest expense of $50 million to $55 million and a full-year tax rate of 26% to 28%. To download the .pdf version of this report, click below. Disclaimer The information contained in this document is provided for informational and marketing purposes only by Mertz Taggart and is not intended as investment, financial, legal, tax, or other professional advice. The content has been compiled using publicly available sources, including but not limited to SEC filings accessed via EDGAR, Seeking Alpha, and Yahoo Finance. While we strive to ensure the accuracy and reliability of the information presented, Mertz Taggart does not warrant or guarantee the completeness, timeliness, or accuracy of the information, nor shall it be held liable for any errors or omissions. This document does not constitute a solicitation, recommendation, or offer to buy or sell any securities or other financial instruments. Any views or opinions expressed are those of the author(s) and do not necessarily reflect the views of Mertz Taggart or its affiliates. Recipients should not rely solely on the information herein for making investment or strategic decisions. All readers are encouraged to conduct their own independent research and to consult with their professional advisors before making any financial or business decisions. All trademarks, logos, and brand names mentioned are the property of their respective owners and are used in this document for identification purposes only.
- Q2 2026 Home-Based Care M&A Report
By Cory Mertz, M&AMI, Managing Partner, Mertz Taggart Published July 21, 2026. Transaction data reflects deals closed between April 1 and June 30, 2026, as tracked by Mertz Taggart At a Glance Home-based care M&A volume stepped down in Q2 2026, with 16 transactions closed during the quarter — down from 27 in Q1 2026 and 29 in Q2 2025. Hospice and home care tied for the lead at 8 closed transactions each, followed by skilled home health at 6. Deal count cooled, but dollar volume did not: General Atlantic's approximately $3 billion acquisition of TEAM Services Group and Kinderhook Industries' $1.1 billion take-private of Enhabit both rank among the largest home-based care transactions on record. New platform formation outpaced add-ons for the first time in years. Home-Based Care M&A Activity in Q2 2026 Home-based care M&A volume stepped down in Q2 2026, with 16 transactions closed during the quarter — down from 27 in Q1 2026 and 29 in Q2 2025. Hospice and home care tied for the lead at 8 closed transactions each, followed by skilled Home Health at 6. Two additional deals were announced but not yet closed as of quarter-end. Two of the quarter’s closings ranked among the largest home-based care transactions on record: General Atlantic’s approximately $3 billion acquisition of TEAM Services Group and Kinderhook Industries’ $1.1 billion take-private of Enhabit. Together they underscore that, even as deal count cooled, large-cap sponsor capital remained firmly committed to scaled home-based care platforms. Cory Mertz, managing partner at Mertz Taggart, noted: “The count came down this quarter, and it’s fair to ask whether the regulatory environment is part of it — the fraud takedowns, the hospice 36-month rule, the new enrollment moratorium and enhanced oversight all make deals more complex to get across the line. But it’s one quarter, and the dollars tell the other side of the story. Sponsors are still writing big checks and, increasingly, looking to return capital to LPs after long hold periods.” How the quarter broke down by buyer type By structure, the quarter comprised six new PE platform investments, four sponsor-backed strategic add-ons, one public-company acquisition, and five post-acute, or independent buyers. New-platform activity outpaced add-ons — a reversal of the add-on-heavy pattern of recent years — as several sponsors established fresh platforms in the sector. Note: Total industry transactions do not necessarily equal the sum of the sub-industries, as many transactions include more than one sub-industry. → Related: Selling a Home Health, Hospice, or Home Care Agency in 2026 Home Health M&A in Q2 2026 Home health saw 6 closed transactions — including two new platform investments, one sponsor-backed add-on, and three other strategic or independent buyers — down from 8 in each of the prior two quarters. Kinderhook Industries completes its take-private of Enhabit The quarter’s headline deal was Kinderhook Industries’ completed take-private of Enhabit, the home health and hospice provider that spun out of Encompass Health in 2022 and spent much of its time as a publicly traded company navigating Medicare home health reimbursement headwinds and investor skepticism. Enhabit shareholders received $13.80 per share in cash — a total enterprise value of roughly $1.1 billion (equity plus roughly $480 million of assumed debt), representing a 10.2x EBITDA multiple on $108 million of EBITDA, a 24% premium to the undisturbed share price and nearly 34% to the 60-day average. Cory Mertz offered this perspective: “The Enhabit deal is a good reminder of why we don’t lead with multiples. Enhabit shareholders received a 10.2x EBITDA, which sounds unremarkable for a billion-dollar, public company. But this was a 24% premium to market and nearly 34% to the 60-day average — significant by any measure.” Other closed home health transactions Among other closings, PruittHealth acquired Georgia Home Health Services, extending its home health presence in South Georgia; Lucent Home Health acquired Chambers Home Health Agency of Northeast Texas, a combined home health and hospice operation; and Renovus Capital Partners-backed Superior Health Holdings added Chant Healthcare, entering Oklahoma across home care, home health and hospice. Heritage Home Health and Hospice and Legacy Hospice formed an Ohio joint venture. Hospice M&A in Q2 2026 Hospice matched home care at 8 closed transactions — three platform investments, two sponsor-backed add-ons, and three strategic or independent buyers — extending the steady, add-on-heavy consolidation that has defined the segment. Webster Equity Partners-backed Bristol Hospice acquired Hope Hospice & Palliative Care, while Norwest made a platform investment in Ennoble Care, a home-based care provider spanning home care and hospice. 5th Century Partners invested in Capstone Hospice, establishing a new platform, and Stillwater Hospice agreed to take over the hospice operations of Campbell County Memorial Hospital. Home Care M&A Non-medical home care tied for the lead at 8 closed transactions — three platform investments, three sponsor-backed add-ons, one public-company deal, and one independent buyer — powered by the quarter’s largest transaction. General Atlantic acquires TEAM Services Group in the quarter's largest deal General Atlantic acquired TEAM Services Group, a San Diego-based, scaled home-based care services company, from Alpine Investors for a reported purchase price of approximately $3 billion — one of the largest home-based care transactions on record. TEAM’s EBITDA was reported, but the transaction’s EBITDA multiple can’t be reliably calculated: only the purchase price is known, not enterprise value. Other closed home care transactions Elsewhere, Warburg Pincus made a platform investment in non-medical home care provider Cornerstone Caregiving, with financing from Monroe Capital; Addus HomeCare acquired HomeCourt Home Care, marking its entry into Indiana; Searchlight Capital Partners-backed Care Advantage added First Priority Home Care; SIG Partners-backed Pillar Health Group acquired Krista Care; and Feature Healthcare acquired Carepoint. Deacon Associates to acquire 31 agencies from HCA Healthcare One of the quarter's most significant announced (but not yet closed) transactions was Deacon Associates' agreement to acquire 31 home health and hospice agencies from HCA Healthcare (NYSE: HCA) , with terms undisclosed. The divested assets span eight states and will be folded into Central Pyramid, a Deacon subsidiary; the portfolio includes agencies HCA had picked up through its 2021 acquisition of an 80% stake in Brookdale Senior Living's health care services segment. The deal is expected to close in roughly three months, pending regulatory approval. It stands out as a large health system stepping back from home-based care even as operators like Deacon — in CEO Trey Crabb's words — "double down on home health and hospice." Cory Mertz added: “For owners weighing a process over the next 12 to 24 months, this environment rewards preparation. Diligence around billing and compliance has only intensified — especially in the enhanced-oversight states — and the sellers who invest early in getting their house in order are the ones who hold their value all the way through to close.” Key Takeaways 16 home-based care transactions closed in Q2 2026, down from 27 in Q1 2026 and 29 in Q2 2025. Hospice and home care tied at 8 closed transactions each; home health closed 6. Deal count fell but dollar volume did not — two of the largest home-based care transactions on record closed during the quarter. General Atlantic acquired TEAM Services Group from Alpine Investors for a reported ~$3 billion, the quarter's largest transaction. Kinderhook Industries took Enhabit private at roughly $1.1 billion enterprise value, a 10.2x EBITDA multiple representing a 24% premium to the undisturbed share price. New platform formation (6 deals) outpaced sponsor-backed add-ons (4), reversing the add-on-heavy pattern of recent years. Regulatory pressure — fraud takedowns, the hospice 36-month rule, the enrollment moratorium, and enhanced oversight — is making deals more complex to close. Deacon Associates agreed to acquire 31 home health and hospice agencies from HCA Healthcare, a large health system stepping back from home-based care. For owners planning a process in the next 12 to 24 months, billing and compliance diligence has intensified, and early preparation is what protects value through to close. If you are interested, you can also download the .PDF version of the Q2 2026 Home-Based Care M&A Report via the following link:
- Why Trust Is the Most Important Factor When Selling Your Treatment Center
Kevin Taggart, CM&AP, Managing Partner, Mertz Taggart At a Glance Selling an addiction treatment center involves more than financials, buyer interest, and timing. Trust between buyer and seller is the variable that most often determines whether a transaction closes, and on what terms. Knowing what questions to ask, and understanding what the buyer needs from you in return, can be the difference between a successful exit and a deal that falls apart in due diligence. There has been considerable M&A activity in the addiction treatment industry in recent years, and with it, more questions from owners about what the process of selling actually looks like. This series addresses those questions. Before considering a sale, owners should understand the factors that can make or break a transaction. Here, we focus on the most consequential one: trust. Seller Beware: What to Ask Before You Commit In any transaction, trust means something narrower than friendship: enough confidence that the other side is acting in good faith, understands what they are buying, and can close. When you are the seller, there are questions worth asking before you go very far: Does my company fit into the buyer’s strategic plan? This may be the most fundamental question. If you cannot understand why a buyer wants your facility or program, that gap will show up in every subsequent step. Ask directly: Have they acquired similar providers before? How do they plan to integrate your facility? Where does your company fit in their broader strategy? A buyer who struggles to answer these questions may not have worked through them yet, and that is worth knowing early. Is the buyer operating in good faith? Pay attention to pace and focus. A buyer who is genuinely interested in closing will keep the process moving. One who seems more interested in learning the details of your business than in advancing the transaction may have different motivations. Does the buyer have the financial capacity to close? This question gets asked less often than it should. Do they have an established fund, a credit facility, or sufficient cash on hand? If they plan to use a combination of debt and equity, can they secure that financing? Do they have a track record of closing transactions on agreed timelines? These are reasonable, direct questions, and a credible buyer will have reasonable, direct answers. Will your legacy and your employees be protected? For many owners, this facility represents something built over years, often with a genuine care mission behind it. Make sure you get a clear answer on how the buyer views your staff and your program’s identity. Employees who have stayed through difficult stretches should be viewed as assets by any serious buyer. → Related: How to Prepare Your Behavioral Health Business for Sale in 2026 The Buyer’s Perspective: What They Need From You It is easy to focus on what you need from the buyer. The transaction goes better when you also understand what they need from you. Buyers typically have three main concerns: Are the financials complete and accurate? The buyer is placing a significant amount of money on a valuation derived from your numbers. Complete and accurate financials are the foundation of that valuation. If they do not hold up through due diligence, expect a renegotiation, and possibly a lost deal. Will the seller stay focused on the business while the transaction is in process? This is a fair concern. M&A processes are time-consuming and distracting by nature. If the business deteriorates while the transaction is moving forward, the buyer has grounds to revisit the valuation. It is in your interest, as much as theirs, to keep operations stable through the process. Are there issues that will surface later if not disclosed now? Pending litigation, payor disputes, compliance concerns, labor issues; these things tend to come out during due diligence regardless. Bringing them forward early allows both parties to work through potential solutions while the deal is still on track. Attempting to conceal them is one of the more reliable ways to collapse a transaction late in the process, when significant time and legal cost have already been committed. → Related: Closing the Deal: Overcoming Common Challenges in Home-Based Care M&A Trust Is a Two-Way Process The further a transaction progresses, the more consequential trust becomes. If either party grows uncomfortable, the transaction is at risk, and by that point, both sides have spent real time and money. Communication is the mechanism that keeps it moving. Get your questions answered early, take the buyer’s concerns seriously, and proceed with care. You have spent years building this treatment center. Make sure you walk away with an outcome worth that. Key Takeaways Trust does not require personal familiarity, but it does require both parties to operate in good faith and communicate clearly. Sellers should ask directly whether the buyer has a coherent strategic rationale for the acquisition, and whether they have the capacity to close. Accurate, complete financials are not optional; they are the foundation of the buyer’s valuation and their confidence in the deal. Issues that surface late in due diligence are far more damaging than issues disclosed early. Transparency reduces deal risk for both sides. Keeping the business stable and focused during the transaction process protects the seller’s valuation as much as anything else. Understanding what the buyer needs from you is as important as knowing what to ask of them. Considering a Sale? Mertz Taggart has been advising healthcare services owners on sell-side transactions for over twenty years, with hundreds of successfully completed deals across behavioral health, home-based care, and related sectors. If you are beginning to think about a sale, a confidential conversation is a reasonable place to start.
- What Financial Goals Must Healthcare Business Owners Achieve Before Exiting?
By Cory Mertz, M&AMI, Managing Partner, Mertz Taggart At a Glance Exiting a healthcare business involves more than finding a buyer and negotiating a price. Most owners face three financial needs that must be addressed before the transaction closes: replacing the earned income the business currently provides, learning to manage a post-exit investment portfolio with a different skill set than running a company, and reducing the concentrated risk that comes from holding most of your net worth in a single illiquid asset. Addressing all three is what allows an owner to exit and stay financially secure afterward. Most owners spend their energy on the transaction itself, which is understandable, but the financial picture after the closing is where things tend to get complicated. The number matters, of course, but so does what the number has to do, and what happens to it once the deal is done. In my experience, owners who think through the following three needs before going to market tend to exit with fewer regrets. 1. Can Your Investment Portfolio Replace Your Business Income? The most immediate question after a sale is whether the proceeds, prudently invested, can generate the income you need to maintain your lifestyle. For many owners, the answer is less straightforward than it first appears. A business that generates $500,000 a year in owner income does not automatically produce a portfolio that does the same. Depending on the sale price, the investment return assumptions, and the tax consequences of the transaction, the post-exit income stream can fall meaningfully short of what the business was producing. That gap is worth understanding before you sign anything. The tax side compounds the issue. A sale creates a significant taxable event, which reduces the net proceeds available to invest. That smaller base then has to generate income at a higher rate to meet the same lifestyle needs, which usually means taking on more investment risk than a conservative portfolio would carry. There is also the question of what the business was quietly subsidizing. Vehicles, insurance, travel, and cell phones often run through the company. After the sale, those expenses shift to personal, and owners who have not mapped that transition tend to underestimate their actual cost of living, sometimes by a substantial amount. 2. Do You Have the Skills to Manage a Portfolio the Way You Ran Your Company? Running a company and managing an investment portfolio require different instincts. The habits that made you effective as an operator, moving quickly on opportunities, staying close to every decision, treating uncertainty as something to act on rather than sit with, can work against you as an investor. Portfolio management tends to reward patience, discipline, and a tolerance for short-term noise. It also involves delegating decisions to advisors whose expertise you have to trust without being able to fully verify it in real time, which is a different relationship than most owners have with their teams. This is not a reason to delay a sale, but it is a reason to build the advisory relationships before the closing, not after. Owners who wait until the wire hits to start thinking about wealth management often make reactive decisions in the first few months that are difficult to undo. → Related: Have an Offer to Buy Your Home Care Agency? What to Do Next 3. How Much of Your Net Worth Is Riding on the Business Right Now? For most healthcare agency owners, the business represents somewhere between 50% and 90% of total net worth. That concentration is the most underappreciated financial risk in the pre-exit period, and it is also the most actionable. Consider three assets, each worth $5 million: a piece of commercial real estate, a cash account, and your agency. All three have the same stated value, but the risk profile of the third is meaningfully different. If your health changes, or a large payer relationship deteriorates, or a regulatory issue emerges, the real estate and cash hold their value. The agency may not. That is not a reason to panic, but it is a reason to think carefully about what risks you can mitigate before going to market. Four areas that consistently matter to buyers: • Key-person insurance • Documented management depth • Diversified payer relationships • Clean compliance records Each of these reduces the fragility of the asset and, in most cases, improves its value to buyers as well. Owners who address these risks before initiating a process tend to command better multiples and face fewer surprises during due diligence. The ones who do not often find that a buyer’s risk assessment knocks down the price in ways that were entirely predictable. → Related: How to Sell Your Home Care Agency: 3 PE Exit Strategies Key Takeaways Replacing business income from a post-exit portfolio is harder than most owners expect, particularly after accounting for taxes on the sale proceeds and expenses previously covered by the company. Managing an investment portfolio requires different instincts than operating a business. Building relationships with qualified advisors before the closing, not after, tends to produce better outcomes. Holding 50–90% of your net worth in a single illiquid asset creates real pre-exit risk. Proactively reducing that risk, through management documentation, payer diversification, and compliance readiness, protects both your financial security and your eventual sale price. All three financial needs are addressable, but they require planning that should begin well before you decide to go to market. One Chance to Get This Right You can get wealthy by building one business well. Staying financially secure after you sell it requires a different kind of planning. The owners who exit on their terms are usually the ones who started thinking about these questions early, before the offers arrived and before the clock was running. Mertz Taggart has guided healthcare owners through hundreds of transactions over more than two decades. If you are thinking about what an exit might look like for your agency, we are glad to have a confidential conversation. There is no obligation and no pressure, just a straightforward discussion of your options. Contact Mertz Taggart for a complimentary, confidential consultation.